
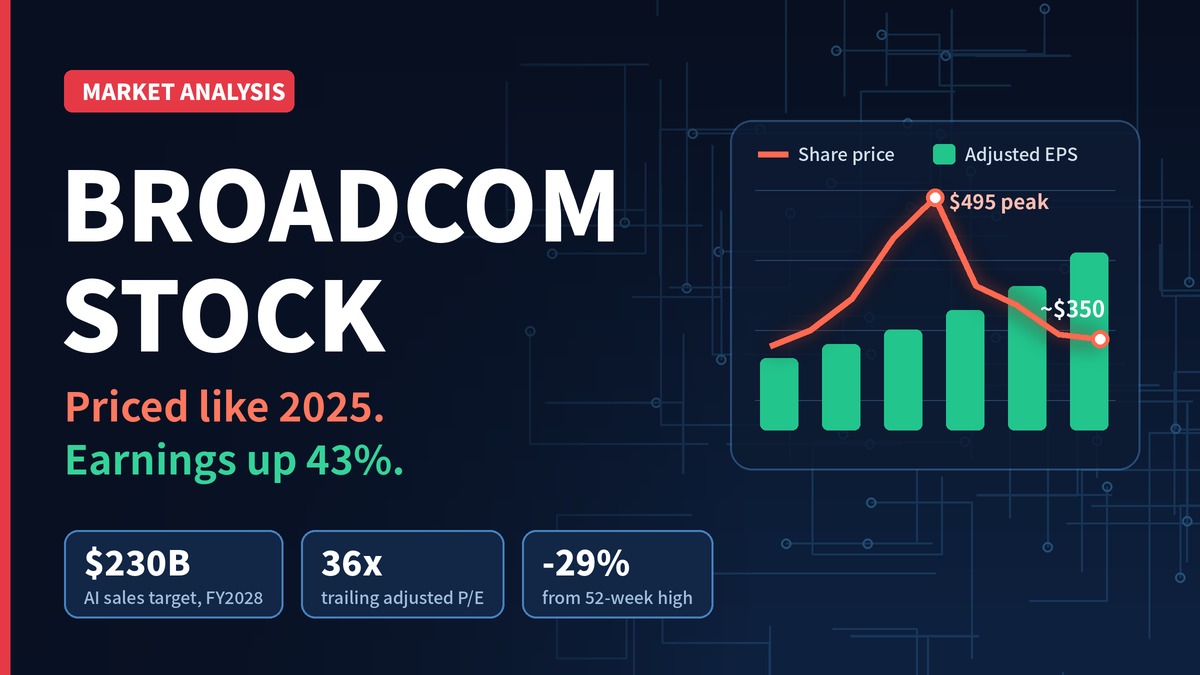
Broadcom Stock is changing hands near $350, roughly 29% below its 52-week high of $495, even after the chip designer raised its artificial intelligence sales outlook with its Sept. 2 earnings report. Earnings keep rising while the share price has barely moved, and that gap now sits at the center of the debate over the company.
Adjusted earnings per share over the past four quarters are running about 43% ahead of fiscal 2025 levels. Yet the shares trade close to where they finished 2025, so buyers today are paying roughly the same price for a considerably more profitable business.
Most of the damage dates back to June. Shares dropped about 13% in the session after the June 3 earnings report, when CEO Hock Tan chose to hold the company’s AI chip forecast steady rather than raise it. That outlook has since moved higher. What still weighs on the stock is how few customers stand behind it.
What Broadcom Now Expects From AI
A higher forecast, plus a new long-range target
At the September report, Broadcom lifted both of the AI revenue figures it had given in June and added a third year to the outlook. Tan said the fiscal 2027 number is supported by supply the company has already secured.
| AI chip revenue outlook | June 2026 guidance | September 2026 guidance |
|---|---|---|
| Fiscal 2026 | About $56 billion | $58 billion |
| Fiscal 2027 | More than $100 billion | About $115 billion |
| Fiscal 2028 | Not given | $230 billion |
Tan also said on the earnings call that Broadcom is on pace to top $30 in adjusted earnings per share in fiscal 2028.
Growth is accelerating every quarter
The current numbers show the business picking up speed. In the fiscal third quarter, which ended Aug. 2, AI chip revenue reached $16.7 billion, up 221% from a year earlier. Profit growth has followed the same path.
| Fiscal 2026 quarter | AI revenue growth (YoY) | Adjusted EPS growth (YoY) |
|---|---|---|
| Q1 | 106% | 28% |
| Q2 | 143% | 54% |
| Q3 | 221% | 96% |
| Q4 (guidance) | 236% (about $21.7 billion) | Not specified |
The Customer Concentration Question
A shrinking base carries more of the load
The market’s main reservation is concentration, and it is getting more pronounced. By Broadcom’s estimate, its top five end customers made up about 55% of revenue in fiscal Q3. That compares with roughly 45% in Q2 and about 40% a year earlier.
Tan counts six custom-chip customers in total. He expects Anthropic to become the largest of them in 2027.
Financing support for two AI labs
For Anthropic and OpenAI, Broadcom set up a financing platform with Apollo and Blackstone to help fund their chip deployments. The company has agreed to backstop as much as about $29 billion of one customer’s lease payments and may also offer residual value guarantees. If either lab has trouble paying for its build-out, a meaningful share of projected fiscal 2027 and 2028 revenue could be delayed. Tan has said the remaining four customers are financially strong enough to fund their own deployments.
Why a single essay moved the stock
How exposed the stock is to individual customers showed up on Sept. 14. Broadcom shares fell around 5% that day after Anthropic CEO Dario Amodei published an essay making the case for a slower pace of AI model development. Tan told CNBC the same day that the discussion had not changed his fiscal 2027 and 2028 targets.
How the Valuation Has Reset
At its record close in early June, Broadcom traded at about 66 times trailing adjusted earnings. At roughly $350, that multiple has fallen to about 36. Over most of the past two years, the stock traded between about 40 and 55 times adjusted earnings. It has dipped below that range only briefly, mostly in spring 2025.
Forward multiples are lower still. Against analyst estimates for fiscal 2027, the shares trade at around 18 times earnings. If Broadcom delivers the $30-plus in per-share earnings Tan is targeting for fiscal 2028, the current price works out to under 12 times earnings. That suggests the market doubts some of the forecast will arrive on schedule.
What Investors Are Weighing
The case for Broadcom Stock rests on the numbers: a raised multiyear forecast, accelerating quarterly growth, and a valuation well below its recent historical range. The case for caution is just as specific. More revenue is tied to fewer customers, and Broadcom now has financial exposure to the funding plans of at least one of them.
The analysis behind these figures concluded that the discount has gone further than the concentration risk justifies. Given how dependent the outlook is on a handful of buyers, it also suggested building a position gradually rather than all at once. Whether Broadcom Stock closes the gap may depend less on AI demand overall and more on whether its largest customers keep securing the capital to take delivery.
Disclaimer: This content was partially produced with the help of AI tools and This content is for informational purposes only and not investment advice.


