
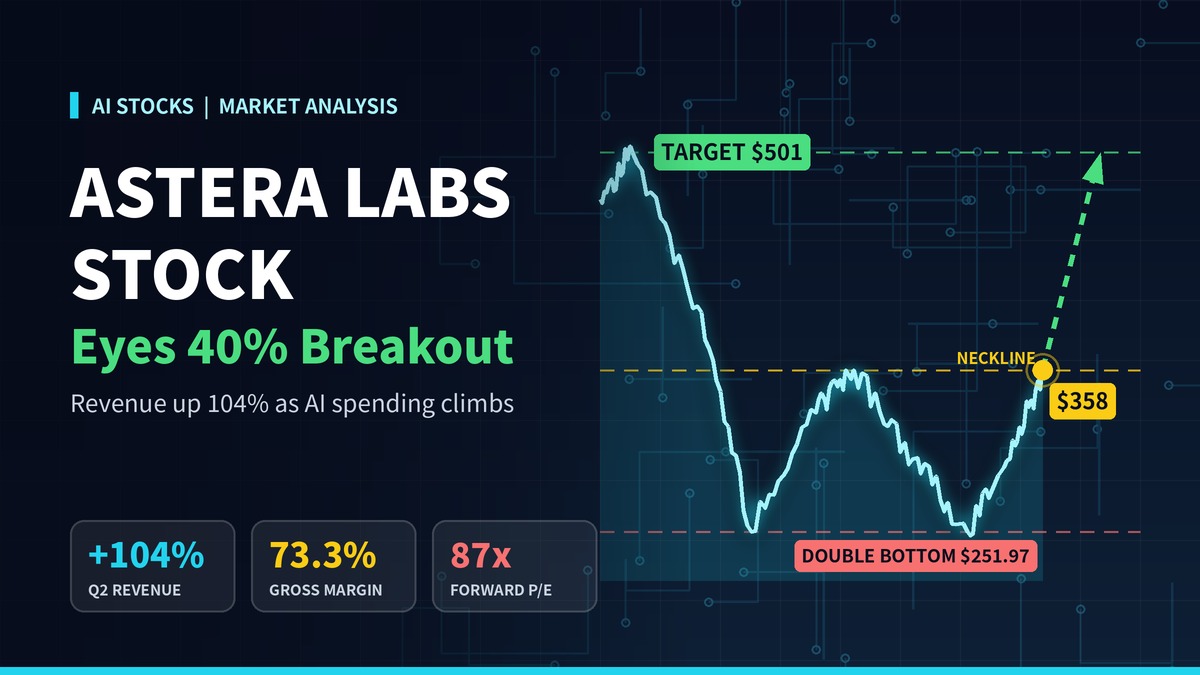
Astera Labs stock has recovered sharply over the past two weeks, climbing from a September 15 low of $251.97 to about $358. The rebound places the AI connectivity company at a price level that has capped its rallies before, and how it trades from here could shape its direction for the rest of the year.
The move amounts to a gain of roughly 42% in about two weeks. It tracks a broader rally among AI hardware suppliers, including optical and networking names such as Corning, Lumentum, and Coherent, as investors return to companies tied to data center construction.
The bigger question is whether the company’s fundamentals can support a valuation that already sits well above its peers. Second-quarter results showed revenue doubling year over year, and analysts expect the next report to show even faster growth.
Why Astera Labs Matters in the AI Buildout
Astera Labs does not make the GPUs that dominate AI headlines. It designs the connectivity hardware that links GPUs, CPUs, memory, storage, and networking equipment inside AI servers and racks. As AI clusters grow larger, moving data quickly between those components has become a performance bottleneck, and that is the problem the company sells into.
Memory products as the next growth lever
Part of the bullish case rests on the company’s Leo product line, which creates a dedicated memory tier attached more directly to GPUs through Astera’s Scorpio switches. In practical terms, the goal is to give AI processors access to more memory without being limited by what fits on each chip. The original report describes the commercial ramp of this technology as a key upcoming catalyst, though the pace of adoption by customers has not been disclosed.
The spending backdrop
Industry forecasts point to a large and expanding market. According to figures cited in the original report, Gartner estimates AI infrastructure spending this year at between $2.59 trillion and $2.67 trillion, up 49% from a year earlier. The report adds that analysts at firms including PwC and Deloitte have raised their outlooks for AI investment. If that spending holds up, suppliers of the plumbing inside data centers stand to benefit alongside the chipmakers.
The Numbers Behind the Rally
Astera Labs’ most recent quarter showed growth that few semiconductor companies of any size can match.
| Metric | Reported or Expected Figure |
|---|---|
| Q2 revenue | $392 million (up 104% year over year) |
| Q2 gross margin | 73.3% |
| Q2 operating margin | 22.7% |
| Next-quarter revenue estimate | $550 million (up 138%) |
| Next-quarter EPS estimate | $1.19 (vs. $0.50 a year earlier) |
| Full-year revenue estimate | $1.91 billion (vs. $852 million last year) |
| Next-year revenue estimate | Over $2.97 billion |
A gross margin above 73% signals pricing power, which matters in a sector where hardware suppliers often face pressure from large, concentrated customers. The rising operating margin suggests the company is beginning to convert top-line growth into profit at a faster clip.
Valuation remains the sticking point
Growth comes at a price. Astera Labs trades at a forward price-to-earnings ratio of about 87, compared with a sector median of 23, according to the original report. Its forward PEG ratio, which adjusts the earnings multiple for expected growth, stands at 1.66 against a sector median of 1.25. Even after accounting for its rapid expansion, the stock is priced more richly than the average peer, leaving little room for a disappointing quarter.
What the Chart Shows
From a technical perspective, Astera Labs stock is at a decision point. It formed what traders call a double-bottom pattern, hitting $251.97 in both July and September before turning higher. The current price of around $358 coincides with the pattern’s “neckline,” the August 4 high that marks the top of the range.
A sustained move above that level would typically be read as confirmation of the pattern. The original analysis also notes that the stock is trading just above the 38.2% Fibonacci retracement level, has moved above the Supertrend indicator, and appears to be forming a bullish pennant.
How the 40% target is derived
The analysis points to $501, the stock’s June high, as the next upside objective. That level sits about 40% above the current price, and the report says it aligns with expectations from analysts at RBC. Technical targets are projections rather than forecasts, however, and a failure to clear the $358 neckline would leave the double bottom unconfirmed and could send shares back toward the middle of their recent range.
What Investors Will Watch Next
The next earnings report is the clearest near-term test. With expectations calling for 138% revenue growth, Astera Labs stock will likely react to guidance on Leo adoption and customer spending plans as much as to the headline figures. Any sign that hyperscalers are slowing data center budgets would weigh heavily on a stock priced at nearly four times the sector’s earnings multiple.
Disclaimer: This content was partially produced with the help of AI tools and This content is for informational purposes only and not investment advice.


