
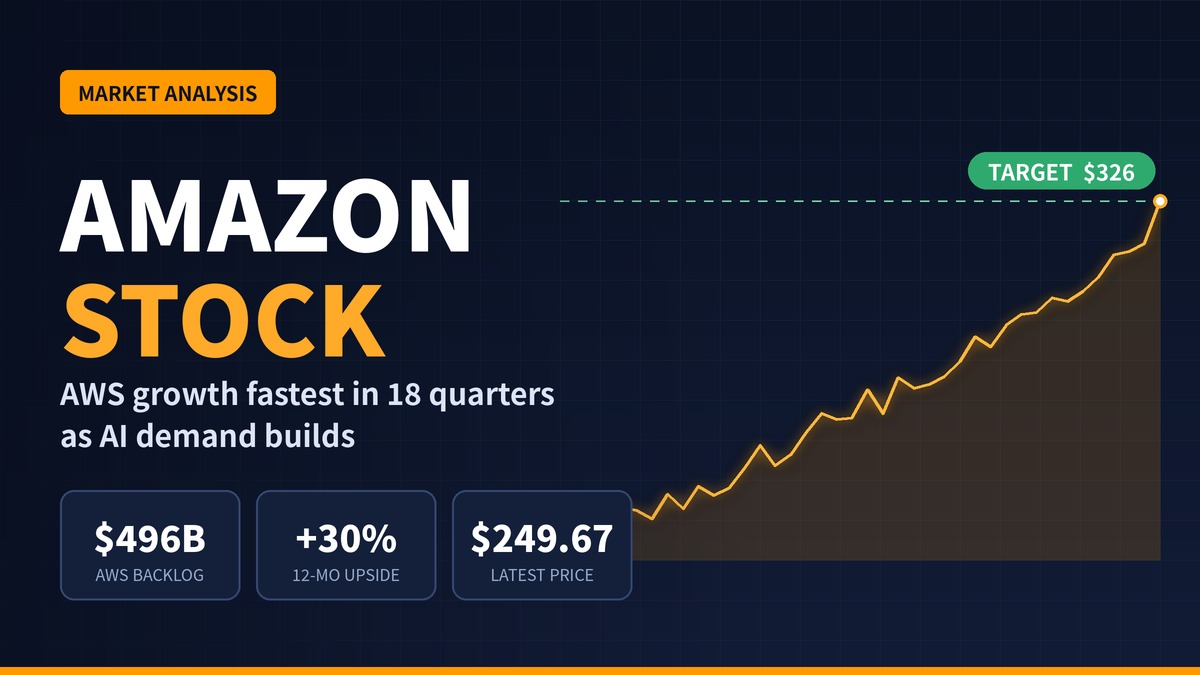
Amazon stock is drawing fresh bullish forecasts after its cloud division posted its strongest growth rate in 18 quarters. A 12-month price projection cited in the report puts the shares at $326.19. Analysts are betting that artificial intelligence will turn Amazon Web Services into an even larger profit engine than it already is.
The size of AWS’s order pipeline is what gives that forecast weight. CEO Andy Jassy pointed to a $496 billion backlog, meaning committed customer contracts not yet recognized as revenue. That backlog, along with strong advertising sales, is the main support for the upbeat outlook.
The optimism has limits. Amazon is spending heavily on data centers and AI infrastructure, and the bull case depends on AWS keeping its current pace. Wall Street consensus still leans toward a buy rating, with some projections reaching $375 if AI momentum holds.
Where the Shares Stand Today
As of September 27, 2026, at 20:41 WIB, Amazon traded at $249.67 on the Pluang investment platform. That quote was recorded on a Sunday, so it reflects the most recent trading session rather than live weekend trading. The stock was up a modest 0.12% on the day, and the company’s market capitalization stood at $2.69 trillion.
The share price sits about 12% below its 52-week high of $284.02. That gap matters for the forecast. Reaching $326.19 would mean not only recovering to the previous peak but also rising roughly 15% beyond it.
| Metric | Figure |
|---|---|
| Latest price (Pluang, Sep 27, 2026) | $249.67 |
| 52-week high | $284.02 |
| Market capitalization | $2.69 trillion |
| 12-month base-case target | $326.19 |
| Optimistic target if AI momentum continues | $375 |
| AWS backlog cited by Andy Jassy | $496 billion |
How the Upside Math Works
The report describes the $326.19 target as a 31.41% increase, which implies it was calculated from a price slightly below today’s quote. Measured from $249.67, the upside is closer to 30.6%. The higher $375 scenario would represent a gain of about 50% from current levels.
Why AWS Is Driving the Amazon Stock Story
Amazon is best known for retail, but investors increasingly value the company on the strength of its cloud business. AWS rents computing power, storage, and AI tools to businesses. Growth there tends to move the stock more than changes in online shopping volumes do.
The division’s fastest expansion in 18 quarters suggests that demand for cloud capacity, much of it tied to AI workloads, is picking up. Jassy described the business as booming. The $496 billion backlog shows that customers have already signed on for years of future spending.
The Trillion-Dollar AI Scenario
The most ambitious part of the bullish case is the idea that AI monetization could eventually push AWS toward $1 trillion in annual revenue. That should be read as a long-range possibility raised in the analysis, not a forecast with a timeline attached. It shows how much of Amazon stock’s future value analysts are tying to AI adoption.
Advertising as a Second Growth Engine
Advertising is the other pillar cited in the report. Amazon sells sponsored product placements and other ad formats across its shopping platform. Strong advertising revenue gives the company a high-margin income stream alongside the cloud business.
The Risks Behind the Bullish Outlook
Amazon’s heavy capital spending cuts both ways. Building data centers and AI infrastructure demands large upfront outlays, and investors will watch closely whether that spending turns into proportional revenue growth.
The whole bullish thesis also rests on AWS sustaining its acceleration. If cloud growth slows or AI demand cools, targets like $326 and $375 would be harder to justify.
What Retail Investors Are Doing
Among Pluang users, sentiment currently tilts toward buying. According to the platform, 68% of order activity on Amazon shares supports buy positions. That figure reflects one platform’s user base and is not a measure of the broader market.
What to Watch Next
For anyone tracking Amazon stock, the next few earnings reports will show whether AWS growth holds and whether the backlog converts into revenue on schedule. Updates on capital spending plans and AI product revenue will be the clearest signals of whether the optimistic scenarios are playing out.
Disclaimer: This content was partially produced with the help of AI tools and This content is for informational purposes only and not investment advice.


